What is the scope and industry significance of the School Management System Market?
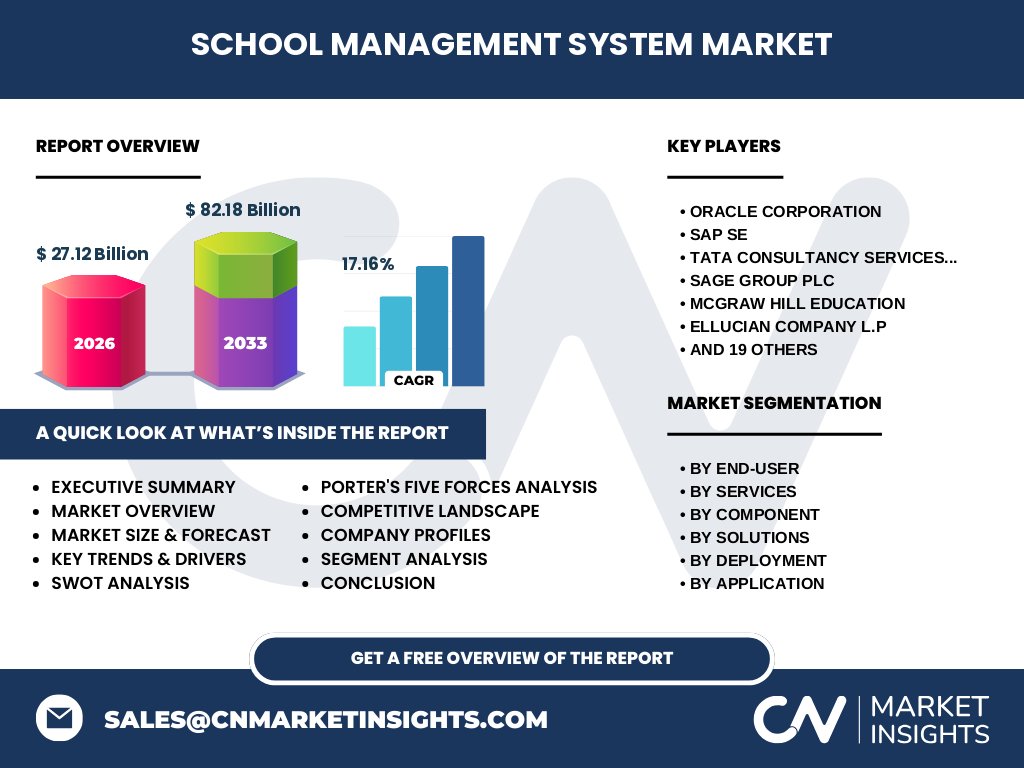
Our analysis indicates that the School Management System Market represents a vital digital transformation vector for global education, valued at $27.12 Billion in 2026. This ecosystem encompasses software and services streamlining institutional workflows, regulatory compliance, and academic delivery across primary, secondary, and higher education sectors worldwide.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating demand for remote learning agility and automated administrative workflows. However, our research highlights significant restraints, including stringent data privacy regulations like FERPA and GDPR, alongside high legacy system integration hurdles that slow down deployment velocity for cash-strapped public institutions.
Emerging Trends Shaping the Industry Landscape
The shift toward cloud-native architectures and AI-driven predictive analytics is redefining institutional capabilities. Industry innovators like PowerSchool Group LLC and Instructure Inc. are embedding machine learning into Student Information Systems to forecast student dropout risks and optimize institutional resource allocation effectively.
How did the COVID-19 pandemic reshape adoption trajectories?
The pandemic served as an unprecedented catalyst, forcing institutions to rapidly adopt cloud hosting and Learning Management Systems to ensure continuity. This emergency pivot permanently elevated digital infrastructure from an optional luxury to a core operational necessity, accelerating long-term market expansion toward our 2027-2033 forecasts.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of enterprise software giants and specialized EdTech specialists. Industry titans like Oracle Corporation and SAP SE compete alongside dedicated players such as Ellucian Company L.P. and Blackboard Inc., driving intense market consolidation through strategic acquisitions and cloud modernization initiatives.
Executive Summary of the School Management System Market
Our comprehensive report reveals a booming sector projected to surge from $27.12 Billion in 2026 to $82.18 Billion by 2033. Exhibiting a robust CAGR of 17.16%, this growth is heavily anchored in cloud migration, robust administrative automation, and surging demand for integrated student success platforms.
Market Forecast and Valuation Trajectory (2027-2033)
Driven by compounding digital adoption across emerging economies, our proprietary models project the market to expand at a 17.16% CAGR, reaching an impressive valuation of $82.18 Billion by 2033. This trajectory reflects sustained institutional investment in scalable cloud infrastructure and advanced academic analytics.
Comprehensive Segmentation Analysis
The market is categorized by components into solutions and services, and further divided by end-users including schools, universities, and community colleges. Deployment models span cloud and on-premise architectures, while application verticals cover administration, academic, learning, and financial management systems designed to optimize institutional workflows.
Regional Market Analysis and Geographic Distribution
North America maintains dominant market share due to early digital maturity and high IT spending in education. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing frontier, fueled by government-backed digitization initiatives in densely populated nations requiring scalable administrative solutions.
In-Depth Regional Review of Key Markets
North American growth is anchored by widespread adoption of advanced Learning Management Systems, whereas European markets prioritize stringent data sovereignty compliance. In contrast, Latin America and MEA exhibit accelerating cloud adoption, led by localized innovators striving to bridge historical educational infrastructure gaps.
Strategic Positioning of Leading Company Profiles
Market leaders leverage distinct strategic advantages. PowerSchool Group LLC dominates K-12 administration, while Ellucian Company L.P. specializes in higher education ERP. Meanwhile, firms like Tata Consultancy Services Limited and SAP SE deliver enterprise-grade integration services tailored for complex, multi-campus university networks.
Porter's Five Forces Analysis of Competitive Pressures
Industry rivalry is intense due to numerous specialized EdTech vendors vying for market share. Supplier power remains moderate given open-source alternatives, whereas buyer power is high as institutions demand bespoke customizations. The threat of substitution is low, cemented by the deeply embedded nature of enterprise academic software.
SWOT Analysis of the Industry Ecosystem
Key strengths include robust recurring SaaS revenue models and high customer retention. Weaknesses involve high initial deployment costs. Opportunities lie in AI-driven predictive learning analytics, while threats stem from escalating cybersecurity vulnerabilities and sophisticated ransomware attacks targeting institutional databases.
Value Chain Analysis from Raw Inputs to End-Users
The value chain originates with raw code, cloud infrastructure providers, and open-source frameworks. Software developers and system integrators transform these inputs into specialized educational solutions, which are subsequently delivered via cloud hosting services to end-users like schools, universities, and community colleges.
High-Potential Investment Insights and Recommendations
Investors should target cloud-hosting and AI-driven examination management solutions, as these segments capture the highest institutional willingness-to-pay. Strategic partnerships with regional system integrators offer the most reliable pathway to scaling market penetration within underserved emerging academic markets.
Conclusion and Strategic Takeaways
The data confirms that the School Management System Market is entering a golden era of expansion, underlined by its 17.16% CAGR. Institutions failing to modernize their administrative and learning management frameworks risk severe operational obsolescence in an increasingly digital academic landscape.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with Chief Information Officers, exhaustive trade registry data, and secondary macroeconomic indicators. This multi-layered approach ensures precise market sizing and reliable long-term forecasting for industry stakeholders.
Scope of the Report and Coverage Parameters
This report covers global revenue streams from 2026 to 2033, evaluating both cloud and on-premise deployments across consulting, system integration, and training services. Exclusions encompass hardware infrastructure hardware manufacturing, focusing strictly on software solutions and associated professional services.
Recent Developments and Industry Announcements
Recent strategic moves feature aggressive merger and acquisition activity, alongside product launches focusing on AI-enhanced student retention modules. Major players like Instructure Inc. and Illuminate Education Inc. have forged critical partnerships with regional education boards to expand their integrated cloud ecosystems.